Selling a House to Move to Florida? Avoid Capital Gains Tax (1031 Exchange Explained)
Inspired by a question from YouTube subscriber Scott in North Carolina, broker Leo Albanes breaks down the federal tax rules for out-of-state buyers moving to Port Charlotte and Punta Gorda: the Section 121 primary residence exclusion ($250k/$500k), 1031 exchanges (for investment or business property only), state clawback rules, and self-directed 401(k) real estate strategies.
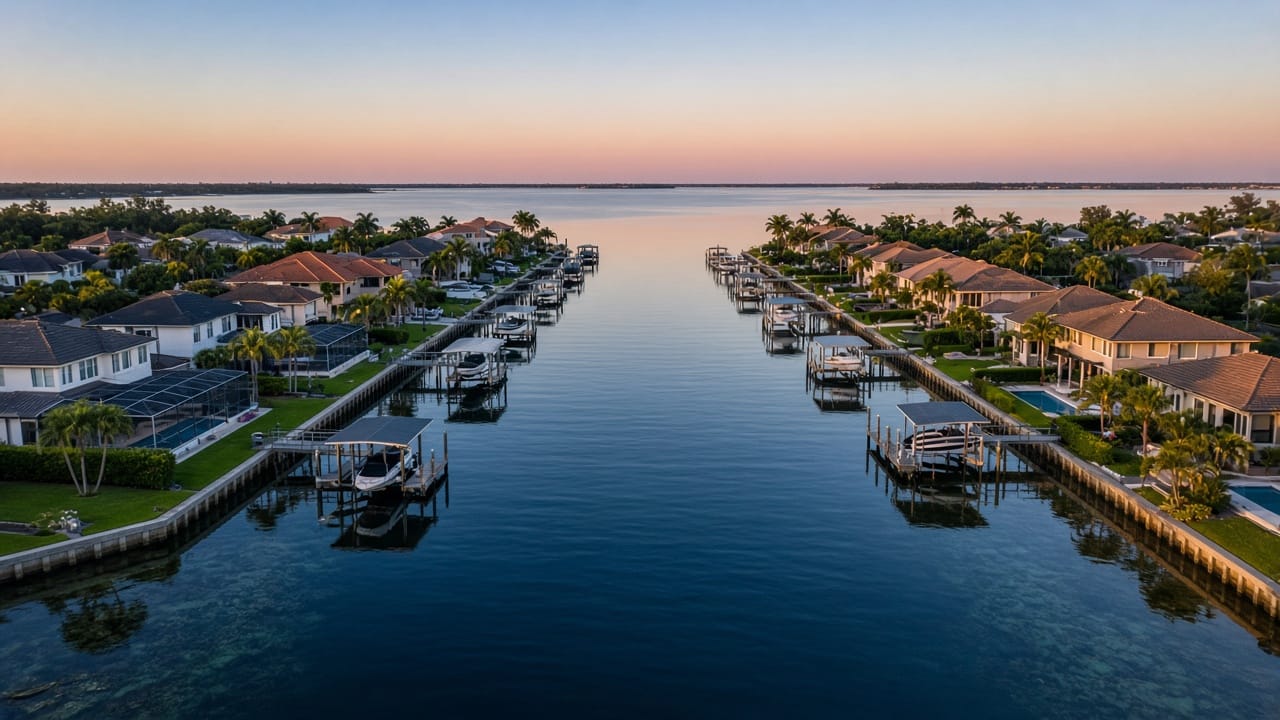
Selling a House to Move to Florida? Avoid Capital Gains Tax (1031 Exchange Explained)
By Leo Albanes, Licensed Florida Real Estate Broker Since 2002 | Charlotte County Properties
My YouTube subscriber Scott from North Carolina recently asked a question I hear almost every week from northern homeowners and investors looking at Port Charlotte and Punta Gorda:
"Leo, if I sell property up North to buy a waterfront home in Charlotte County, am I stuck losing a huge chunk of my equity to capital gains taxes before I even get to Florida?"
When Scott and I walked through the numbers, he saw three distinct federal tax pathways inside the Internal Revenue Code (IRC) that apply whether you are moving to Southwest Florida from North Carolina, New York, New Jersey, California, Illinois, Ohio, Michigan, Pennsylvania, Massachusetts, or any other state.
The key is never mixing these three buckets together: selling your primary residence, selling an investment property or land, and using a 401(k) or IRA follow three separate sections of federal tax law.
1. Selling Your Primary Residence: The IRC Section 121 Exclusion ($250,000 / $500,000 Tax-Free)
If you are selling your primary residence, you do not use a 1031 exchange. Primary homes fall under IRC Section 121, which permanently eliminates tax on qualified gains: Up to $250,000 of capital gain tax-free (single), or Up to $500,000 of capital gain tax-free (married filing jointly).
How to Qualify for the Section 121 Exclusion
- 2-of-5-Year Ownership Test: You owned the home for at least 24 months (2 years) out of the 5 years before closing.
- 2-of-5-Year Use Test: You lived in the home as your principal residence for at least 24 months (730 total days) during that 5-year window. For married couples claiming $500,000, one spouse must meet the ownership test, while both spouses must meet the residency test.
- 2-Year Lookback Rule: Neither spouse claimed Section 121 on another sale during the prior 2 years.
Special Protections: Surviving Spouses and Partial Exclusions
- Surviving Spouse Rule (
IRC Section 121(b)(4)): A widowed owner selling within 2 years of a spouse's passing (without remarrying) keeps the full $500,000 cap if both met the 2-year tests before death. - Partial Exclusion (
IRC Section 121(c)): Selling before 24 months for a doctor-recommended health move, a job relocation 50+ miles away, or an unforeseen hardship qualifies for a pro-rated cap (12 months = 50%, or $250,000 married).
How Adjusted Cost Basis Protects Gains Above $500,000
Your taxable gain is your net sale price (after commissions, transfer taxes, and title fees) minus your adjusted cost basis (original purchase price + acquisition closing costs + documented capital improvements).
Real-World Example: A married couple in Raleigh bought their home 15 years ago for $300,000 and sells it for $920,000 ($620,000 gross gain). After adding $100,000 in documented capital improvements ($45,000 kitchen remodel, $22,000 roof, $15,000 HVAC, $18,000 deck/windows) and deducting $55,000 in selling costs, their net gain drops to $465,000. Because $465,000 sits below the $500,000 Section 121 cap, they owe $0 in federal capital gains tax with no reinvestment deadline.
2. Selling a Rental, Land, or Commercial Property: The IRC Section 1031 Tax-Deferred Exchange
When selling a rental house, duplex, vacation rental, farm parcel, raw land, or commercial building, IRC Section 1031 applies. A 1031 exchange is strictly for real property held for business or investment; personal residences do not qualify.
The Four Taxes a 1031 Exchange Defers at Once
Selling an appreciated investment property outright triggers up to four stacked tax bills: 1. Federal Long-Term Capital Gains Tax: 15% or 20% based on your income bracket. 2. Depreciation Recapture Tax (IRC Section 1250): Up to 25% on every dollar of depreciation deducted over your ownership period. 3. Net Investment Income Tax (NIIT, IRC Section 1411): An extra 3.8% surtax above $200,000 MAGI (single) or $250,000 (married). 4. State Capital Gains Tax: Your origin state's rate on real estate gains.
Real-World Example: Suppose Scott sells a North Carolina rental property for $600,000 that he bought for $250,000, after claiming $90,000 in depreciation. Without a 1031 exchange, he owes 25% depreciation recapture on the $90,000 ($22,500), federal capital gains and 3.8% NIIT on the $350,000 economic gain (~$65,000 to $83,000), plus state income tax (~$17,000+), totaling over $105,000 in tax. By executing a 1031 exchange into a Charlotte County investment property, 100% of that $105,000+ stays in his purchasing power.
What Qualifies as "Like-Kind" Real Estate?
Any U.S. investment or business real property can be exchanged for any other U.S. investment or business real property: A northern rental house or duplex into a waterfront vacation rental or long-term rental in Port Charlotte or Punta Gorda. Raw investment land or farmland up North into income-producing residential or commercial property in Southwest Florida. * A fractional Delaware Statutory Trust (DST) (Rev. Rul. 2004-86) for passive income without landlord duties.
The 5 Ironclad Rules of a Valid 1031 Exchange
- Qualified Intermediary (QI) Before Closing: You can never have constructive receipt of sale funds; your QI must be assigned before your northern closing.
- 45-Calendar-Day Identification Window: Within 45 calendar days of closing (including weekends/holidays), identify replacement property in writing to your QI under the 3-Property Rule (up to 3 properties of any value), the 200% Rule (4+ properties up to 200% of sold value), or the 95% Exception (acquire 95%+ of identified value).
- 180-Calendar-Day Closing Window: Close within 180 calendar days of your sale (or by your tax return due date with extensions, if earlier).
- Reinvest All Equity & Replace Debt (Zero "Boot"): Buy equal or greater value, reinvest 100% of net cash, and replace any paid-off debt with equal/greater debt (or fresh cash). Leftover cash (cash boot) or debt reduction (mortgage boot) is taxable.
- No Federal Dollar Cap: Section 1031 has no dollar limit.
Reverse Exchanges & the 2-Year Safe Harbor for Future Retirement Homes
- Reverse 1031 Exchange (
Rev. Proc. 2000-37): If you find the right waterfront home in Punta Gorda Isles or Port Charlotte before your northern rental sells, an Exchange Accommodation Titleholder (EAT) holds title to the Florida property first, giving you 45 days to identify your northern rental for sale and 180 days to close it. - Converting a 1031 Rental Into Your Future Retirement Home (
Rev. Proc. 2008-16+IRC Section 121(d)(10)): Under the Revenue Procedure 2008-16 Safe Harbor, if you acquire a Charlotte County home via a 1031 exchange and rent it at fair market value for at least 14 days in each of two consecutive 12-month periods (24 months total) while capping personal use at the greater of 14 days/year or 10% of rental days, you can convert it into your primary residence after Month 24 without triggering deferred 1031 tax. (UnderIRC Section 121(d)(10), you must hold a converted 1031 home for 5 total years before claiming Section 121 on a later sale, with post-exchange rental periods pro-rated as non-qualified use.)
3. Using a 401(k) or IRA: Why Retirement Accounts and Personal 1031 Exchanges Never Mix
A 401(k) or IRA and a personal 1031 exchange live in separate legal silos and cannot be combined.
- You Cannot Mix Funds: A personal 1031 exchange applies only to investment real estate held in your personal name, revocable trust, or single-member LLC. You cannot use 401(k) or IRA funds inside a personal 1031 exchange.
- Prohibited Transactions (
IRC Section 4975): Federal law bars self-dealing between your retirement plan and a disqualified person (you, your spouse, parents, and descendants). You cannot sell personal property to your plan, pay plan expenses personally, or stay in a plan-owned property for even one night.
Two Legal Paths to Use Retirement Funds for Florida Real Estate
- Self-Directed Solo 401(k) or SDIRA for Investment Property: Your plan trust buys a Port Charlotte or Punta Gorda rental or lot directly. Because the account is tax-sheltered, no 1031 exchange is needed inside the plan; all rent and gains stay tax-deferred (or 100% tax-free in a Roth Solo 401(k) / Roth SDIRA). With a non-recourse loan, a Solo 401(k) is exempt from UDFI / UBIT tax under
IRC Section 514(c)(9), while a leveraged SDIRA owes UDFI tax. - 401(k) Participant Loan (
IRC Section 72(p)) for a Personal Down Payment: Borrow up to the lesser of $50,000 or 50% of your vested balance tax-free and penalty-free toward your home purchase. Cashing out before age 59½ (or age 55 after leaving that employer) triggers ordinary income tax plus a 10% penalty.
4. State-by-State Tax Rules: Florida vs. North Carolina vs. Other Origin States
- Florida (Destination State): 0% state income and capital gains tax (Florida Constitution), no 1031 clawback, no state nonresident withholding (only federal FIRPTA for foreign sellers), and $0.70 per $100 (
0.70%) documentary stamp tax outside Miami-Dade (not deferred by a 1031). Once domiciled in Charlotte County, file for the Florida Homestead Exemption by March 1 for up to $50,000 off assessed value plus the 3% annual Save Our Homes (SOH) cap. - North Carolina (Scott's Origin State): Follows federal Section 121 AGI, taxes capital gains above the cap at NC's flat rate, conforms to federal Section 1031 with no out-of-state clawback, has no nonresident withholding for U.S. residents (buyer files
Form NC-1099NRSwithin 15 days of closing), and charges $1.00 per $500 (0.20%) deed excise tax (not deferred by a 1031). - Other Origin States: CA, MA, OR, and MT track out-of-state 1031 exchanges via annual clawback filings and tax the deferred gain if you later cash out. NY, NJ, MD, CA, SC, ME, VT, RI, and GA require nonresident tax withholding or exemption affidavits at closing.
5. Matching Your Tax Capital to Charlotte County Waterfront Fundamentals
Preserving $50,000 to $150,000 of equity changes what you can buy on the water in Port Charlotte (33948, 33952, 33953, 33954, 33981) and Punta Gorda (33950, 33955, 33980, 33983): 1. Bridge Clearance & Harbor Access: Bridge clearance in feet (10-ft bridges in Port Charlotte powerboat canals and 13-ft fixed bridges in Punta Gorda Isles powerboat canals; always check clearance for your boat) versus no-bridge sailboat water out to Charlotte Harbor and the Gulf of America in Punta Gorda Isles (PGI), Burnt Store Isles (BSI), and Port Charlotte. 2. Seawall Responsibility: City-maintained seawalls in PGI and BSI versus privately maintained seawalls in Port Charlotte and South Gulf Cove. 3. Flood Zone & Insurance Engineering: Comparing X flood zones and high-elevation AE lots alongside wind-mitigation credits (hip roofs, impact glass, secondary water barriers). 4. 45-Day Identification Backup List: Selecting three vetted Charlotte County properties during your 45-day 1031 window so you have two inspected backups ready.
Frequently Asked Questions
Can I sell my primary home up North and my northern rental property at the same time?
Yes. Sell your northern primary residence under IRC Section 121 (up to $250,000 single / $500,000 married tax-free to buy your Florida home), while placing your northern rental or land sale through a Qualified Intermediary under IRC Section 1031 to acquire a Charlotte County income property with zero current capital gains or depreciation recapture tax.
What happens if I hold a 1031 rental in Florida until I pass away?
Under IRC Section 1014, holding your 1031 replacement property until death gives your heirs a full step-up in cost basis to fair market value on the date of death, permanently wiping out both the deferred capital gains and all accumulated depreciation recapture.
Let's Map Out Your Move or 1031 Timeline Together
I am a licensed Florida real estate broker (since 2002), not a CPA or tax attorney, so always have your CPA, tax attorney, and Qualified Intermediary verify your numbers before listing. Once your tax plan is set, I handle the Charlotte County waterfront side so every deadline, bridge height, seawall, and valuation lines up.
- Talk to Leo Albanes, local broker since 2002: Call or text (941) 337-3391
- Browse live Charlotte County MLS listings: CharlotteCountyProperties.com
- Free Charlotte County Relocation Guide: CharlotteCountyProperties.com/relocation-guide
Leo Albanes
Broker-Owner, Charlotte County Properties Inc.
Florida Real Estate Broker License #BK3054900
Over 20 years helping buyers, sellers, and investors navigate Charlotte County. Punta Gorda-based. Se habla español.